Crypto exchange compliance means holding the right licence in every market you serve and running the controls regulators require: KYC, transaction monitoring, sanctions screening, Travel Rule data sharing, capital, custody and tax reporting. In October 2026 that means a MiCA CASP authorisation in the EU, FinCEN registration plus state licences in the US, FCA registration today and an FCA authorisation application before 28 February 2027 in the UK, and licences from VARA, MAS or FIU-IND elsewhere.
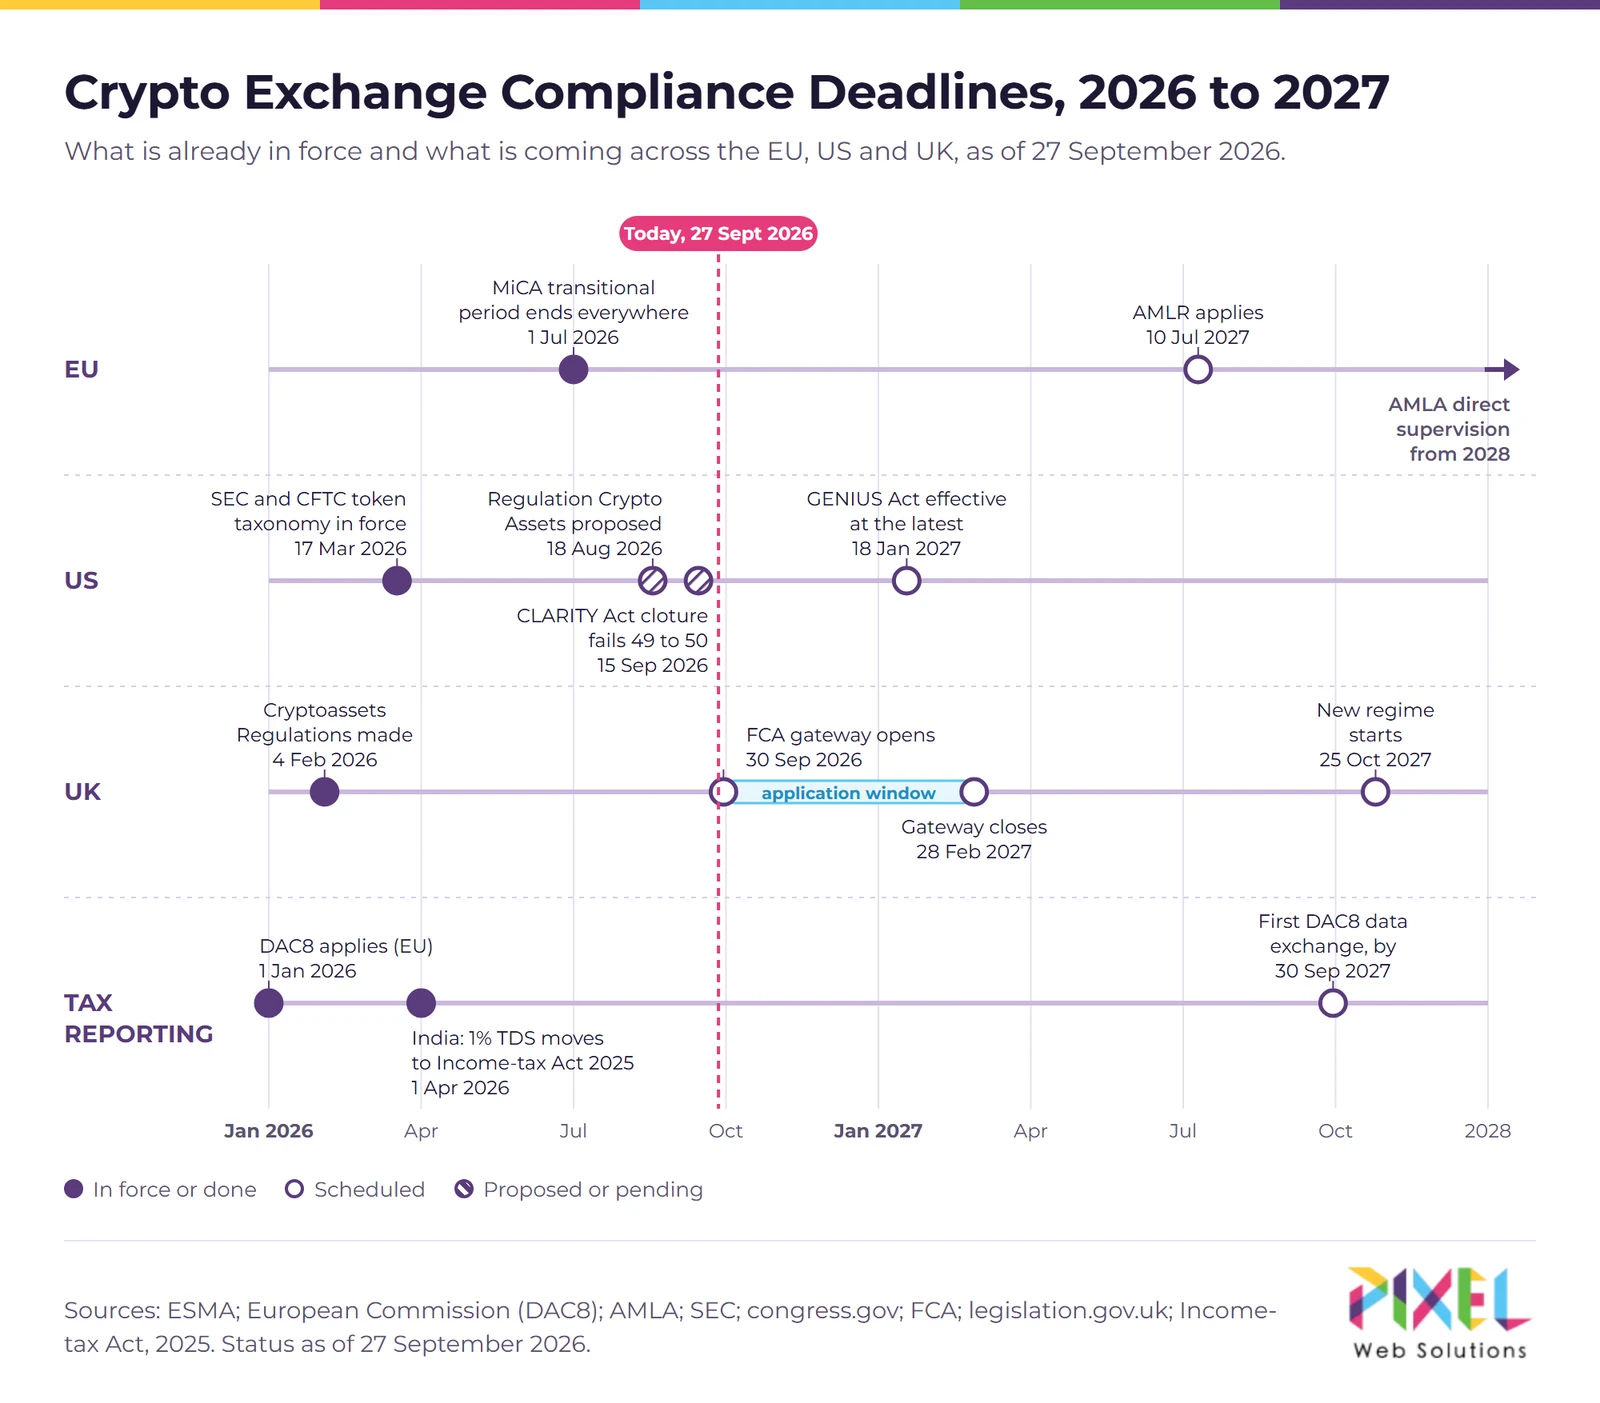
Crypto exchange regulations have moved faster in the last 22 months than in the five years before. The EU's Markets in Crypto-Assets Regulation (MiCA) has applied in full since 30 December 2024, and its transitional period ended on 1 July 2026. In the United States, the GENIUS Act became the first federal crypto statute in July 2025, the SEC and CFTC published a token taxonomy in March 2026, and the OCC finalised its GENIUS Act rule on 21 October 2026. The UK opened its authorisation gateway on 30 September 2026, and India's FIU-IND served notices on 15 more offshore exchanges in September 2026.
For founders, creating a crypto trading platform that meets these rules can still feel like a nightmare. This guide sets out who regulates crypto exchanges, what each regulator requires as of 26 October 2026, how to get a cryptocurrency exchange licence in the United Kingdom, what centralized exchange compliance requirements look like as a checklist, and how each rule turns into a feature your exchange software must have.
Key Takeaways
- The EU grace period is over: MiCA's transitional period ended across the EU on 1 July 2026, and ESMA told unauthorised firms to wind down EU business. ESMA's interim register listed about 385 authorised CASPs on 22 October 2026, with Germany (117), France (36) and the Netherlands (29) home to the most.
- US rules are clearer but not finished: the GENIUS Act (stablecoins) is law and the OCC issued its final implementing rule on 21 October 2026, the SEC and CFTC token taxonomy took effect in March 2026, but the CLARITY Act for market structure is still pending after a Senate procedural vote failed on 15 September 2026.
- The UK gateway is open: FCA authorisation applications run from 30 September 2026 to 28 February 2027, the regime starts on 25 October 2027, a trading platform application costs £28,150 and needs at least £150,000 of permanent minimum capital. Existing FCA registration does not convert automatically.
- Travel Rule is near-universal: 91 of 109 jurisdictions assessed by FATF had passed Travel Rule laws by July 2026, and the EU applies it to crypto transfers of any amount.
- Compliance failures are software failures: Coinbase Europe was fined €21.5 million because a misconfigured monitoring system missed more than 30 million transactions.
What Are Crypto Exchange Regulations?
Crypto exchange regulations are the rules that define how crypto exchanges must be set up and operated within a regulated framework. Every country has its own financial laws and builds its crypto rules on top of them, so regulations for cryptocurrency exchanges vary from country to country. The goal is the same everywhere: stop illegal activity and protect people's funds.
Regulatory bodies write and enforce these rules. Their work covers AML (Anti-Money Laundering) and CFT (Combating the Financing of Terrorism) policies, crypto exchange licences, capital and custody requirements, market conduct and consumer protection. Cryptocurrency exchange compliance is the exchange's side of that relationship: the licences it holds, the controls it runs and the records it keeps to prove it follows the rules.
Is Cryptocurrency Regulated by the Government?
Yes, in every major market, although the shape differs. The EU regulates crypto-asset services directly under MiCA. The US regulates through existing money transmission, securities, commodities and (since 2025) stablecoin laws spread across federal and state agencies. The UK, UAE, Singapore, Hong Kong and India each run their own licensing or registration regimes. What no major market offers in 2026 is an unregulated space for an exchange that serves retail customers.
Who Regulates Crypto Exchanges? The Major Regulatory Bodies
Each country has its own regulators for crypto trading, and a few global bodies set the standards they follow. The most important regulatory bodies for crypto exchanges are:
- FATF (Financial Action Task Force), the global AML standard-setter
- SEC (Securities and Exchange Commission) and CFTC (Commodity Futures Trading Commission) in the US, with FinCEN for AML and state regulators such as NYDFS for licences
- FCA (Financial Conduct Authority) in the UK
- ESMA (European Securities and Markets Authority) and national competent authorities in the EU
- VARA in Dubai, ADGM's FSRA in Abu Dhabi, MAS in Singapore and FIU-IND in India
FATF
FATF, or the Financial Action Task Force, is an inter-governmental body that sets global standards against money laundering and terrorist financing. It does not license exchanges itself, but almost every national crypto rule traces back to its Recommendation 15 on virtual assets and its Travel Rule. FATF maintains two lists:
- Black list (high-risk jurisdictions subject to a call for action): countries with serious strategic deficiencies. As of the June 2026 plenary, the list is North Korea (DPRK), Iran and Myanmar.
- Grey list (jurisdictions under increased monitoring): countries working with FATF to fix deficiencies. Kenya remains on it, Bosnia and Herzegovina and Iraq were added in June 2026, and Algeria and Namibia were removed, leaving 22 jurisdictions. The Philippines, once on this list, was removed in February 2025.
FATF reviews both lists at each plenary, and its October 2026 plenary was under way as this guide was updated, so check the outcomes page before you hard-code country risk scores. Screen every user and counterparty against these lists and apply enhanced due diligence to grey-list exposure. FATF's July 2026 targeted update found that 91 of 109 jurisdictions (83%) had passed Travel Rule legislation, yet almost half of them had taken no supervisory or enforcement action. In June 2025 FATF also revised Recommendation 16 on payment transparency, with changes due to take effect by the end of 2030.
SEC
The SEC, or Securities and Exchange Commission, was created after the 1929 crash to keep securities markets fair and efficient. It regulates exchanges, brokers, dealers and advisers that deal in securities, and it is led by five commissioners appointed by the US President and confirmed by the Senate. Its key responsibilities include:
- Overseeing corporate disclosure
- Enforcing securities laws
- Facilitating capital formation
- Protecting investors
For crypto exchanges, the question is which tokens are securities. The SEC launched a Crypto Task Force led by Commissioner Hester Peirce on 21 January 2025. On 17 March 2026 it issued an interpretation, joined by the CFTC, with a token taxonomy of five categories: digital commodities, digital collectibles, digital tools, stablecoins and digital securities. SEC Chairman Paul Atkins said the interpretation recognises that most crypto assets are not themselves securities.
On 18 August 2026 the SEC went further and proposed Regulation Crypto Assets, with two offering exemptions (up to $5 million over four years, and up to $75 million per 12 months) and a conditional safe harbour from the "investment contract" definition. The comment period ran for 60 days after Federal Register publication, and as of 26 October 2026 it is still a proposal, not a rule in force. For how token type affects listing decisions, see our guide to utility tokens vs security tokens.
FCA
The UK's FCA, or Financial Conduct Authority, is the independent regulator of the UK's financial markets, accountable to HM Treasury and Parliament. Its operational objectives are:
- To promote healthy competition in financial markets
- To protect consumers, including crypto users
- To enhance the integrity of the UK financial system
The FCA has supervised cryptoasset businesses for AML since 10 January 2020, so any exchange serving UK customers must be registered with the FCA today. The UK Travel Rule has applied since 1 September 2023, and strict crypto marketing rules since 8 October 2023.
A full authorisation regime is coming, and the application window is now open. The Financial Services and Markets Act 2000 (Cryptoassets) Regulations 2026 were made on 4 February 2026 and commence in full on 25 October 2027. The FCA's application gateway opened on 30 September 2026 and closes on 28 February 2027, and registered firms get no automatic conversion: they must apply. The detailed rules are in the FCA's June 2026 policy statements. The full UK licence section below turns these into fees, capital and a step-by-step plan.
ESMA
ESMA, the European Securities and Markets Authority, is the EU agency that promotes stable and orderly financial markets and investor protection. Its three main objectives are:
- Investor protection
- Financial stability
- Orderly markets
Under MiCA, ESMA writes technical standards, coordinates national regulators and keeps the EU register of crypto-asset service providers (CASPs). The licence itself comes from a national competent authority in one member state, such as BaFin in Germany or the AMF in France, and then passports across the EU. ESMA's interim MiCA register, last updated on 22 October 2026, lists about 385 authorised CASPs (388 register entries). Germany leads with 117, followed by France (36), the Netherlands (29), Cyprus (25) and Malta (23).
These regulators revise their rules often, so compliance is a continuing job, not a one-time filing.
Crypto Exchange Regulations by Country: What Is in Force in October 2026
Competitor guides list regulators; few tell you which rules are actually in force today. This table does, as of 26 October 2026.
| Jurisdiction | Regulator and licence | Status on 26 Oct 2026 | Key dates |
|---|---|---|---|
| European Union | National authority, MiCA CASP authorisation under Regulation (EU) 2023/1114 | In force; transitional period over | Full application 30 Dec 2024; all grandfathering ended 1 Jul 2026 |
| EU AML | Anti-Money Laundering Authority (AMLA), AMLR | Adopted, applies later | AMLR applies 10 Jul 2027; AMLA direct supervision from 2028 |
| United States (federal) | FinCEN MSB registration | In force | Crypto exchangers are money transmitters under FinCEN guidance FIN-2019-G001 |
| United States (securities) | SEC and CFTC token taxonomy | In force (interpretation) | Issued 17 Mar 2026; Regulation Crypto Assets proposed 18 Aug 2026 |
| United States (stablecoins) | GENIUS Act (S.1582) | Law, effective 18 Jan 2027; OCC final rule issued 21 Oct 2026 | Signed 18 Jul 2025; OCC rule and Act take effect 18 Jan 2027; AML and sanctions rules still to come from Treasury |
| United States (market structure) | CLARITY Act (H.R.3633) | Pending | Passed House 17 Jul 2025; Senate cloture vote failed 49 to 50 on 15 Sep 2026 |
| United States (states) | State money transmitter licences; NY BitLicense issued by NYDFS | In force | BitLicense since 2015; 31 states have enacted the Money Transmission Modernization Act in full or part |
| United Kingdom | FCA MLR registration now; FCA FSMA authorisation next | Registration in force; authorisation gateway open | Gateway 30 Sep 2026 to 28 Feb 2027; regime starts 25 Oct 2027 |
| UAE (Dubai) | VARA VASP licence | In force | VARA set up under Dubai Law No. 4 of 2022; rulebooks v2.0 compliance from 19 Jun 2025; reserve assets audit circular 6 Oct 2026 |
| UAE (Abu Dhabi and onshore) | ADGM FSRA; federal Capital Market Authority (formerly SCA) | In force | ADGM regime since 2018; CMA replaced the SCA on 1 Jan 2026 |
| Singapore | MAS licence under the Payment Services Act; DTSP licence under FSMA | In force | Since 30 Jun 2025, firms serving only overseas clients need a licence MAS "will generally not issue" |
| India | FIU-IND registration as a PMLA reporting entity | In force; enforcement active | Notified in the Gazette on 7 Mar 2023; notices to 15 offshore VDA SPs on 9 Sep 2026; 1% TDS and 30% tax on gains |
| Hong Kong | SFC VATP licence; HKMA stablecoin licence | In force | VATP regime since 1 Jun 2023; HKMA stablecoin regime since 1 Aug 2025 |
For licence costs and approval timelines by country, see our crypto exchange development cost guide, and for the launch sequence, our guide on how to start a cryptocurrency exchange.
MiCA CASP Capital Requirements and Transitional Periods
MiCA sets a minimum permanent capital for every CASP, in three classes under Annex IV. Article 67 requires the higher of the class minimum or one quarter of the previous year's fixed overheads.
| Class | Minimum capital | Services it covers |
|---|---|---|
| Class 1 | €50,000 | Executing, receiving and transmitting orders; placing crypto-assets; transfer services; advice; portfolio management |
| Class 2 | €125,000 | Class 1 services plus custody, and exchange of crypto for funds or for other crypto |
| Class 3 | €150,000 | Class 2 services plus operating a trading platform |
A full order-book exchange is a Class 3 CASP, so budget at least €150,000 of permanent capital, and more if a quarter of your fixed overheads is higher.
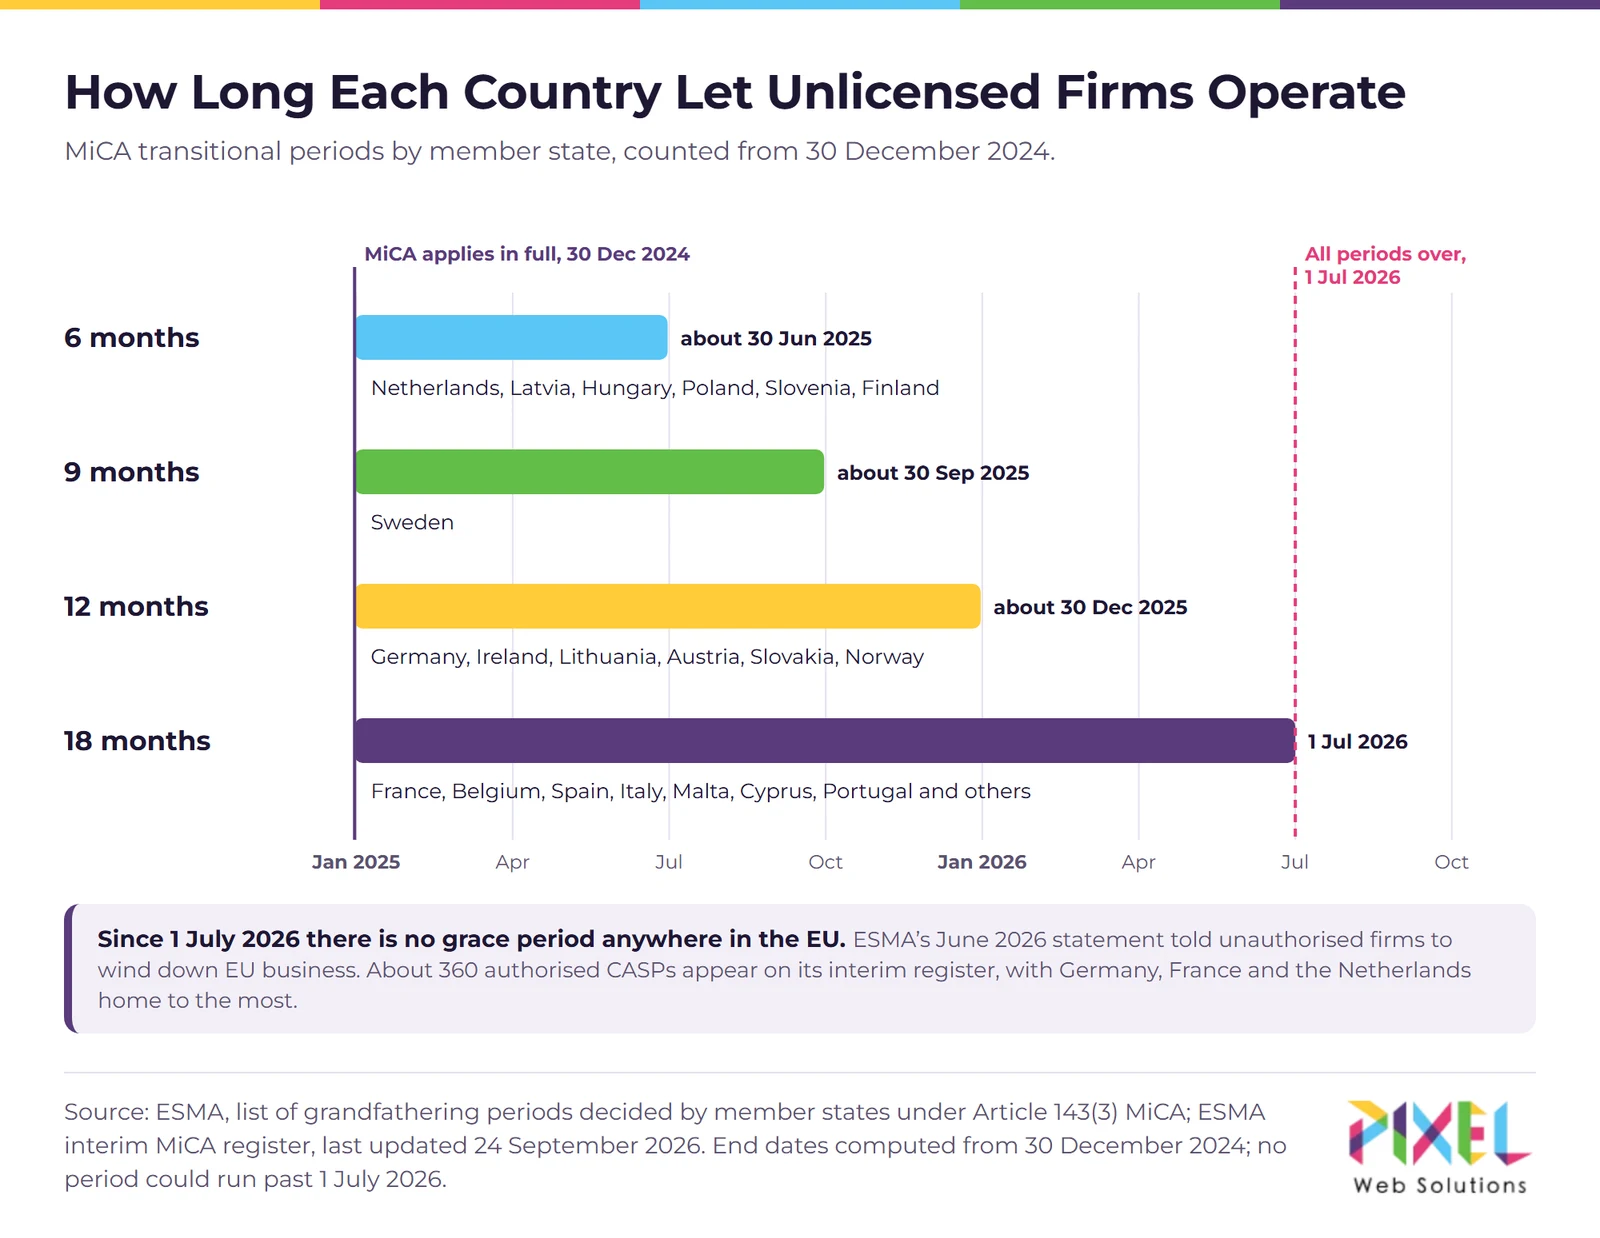
The transitional period allowed existing providers to keep operating while they applied, up to 1 July 2026 at most. Member states could shorten it, and ESMA's list shows four choices: 6 months (Netherlands, Latvia, Hungary, Poland, Slovenia, Finland), 9 months (Sweden), 12 months (Germany, Ireland, Lithuania, Austria, Slovakia, Norway) and 18 months (France, Belgium, Spain, Italy, Malta, Cyprus, Portugal and others). All of them have now ended, and ESMA's June 2026 statement told firms without authorisation to wind down EU business in an orderly way.
The Travel Rule: FATF, EU, US and UK
The Travel Rule requires an exchange to send identifying information about the sender and recipient along with a crypto transfer to another provider. The thresholds differ:
| Regime | Threshold | Notes |
|---|---|---|
| FATF standard | USD/EUR 1,000 de minimis allowed | Below it, lighter data is permitted |
| EU Transfer of Funds Regulation (2023/1113) | No threshold for transfers between CASPs | Applies since 30 Dec 2024; for transfers over €1,000 to or from a self-hosted wallet, verify the customer owns or controls it |
| United States | $3,000 | FinCEN's funds Travel Rule, applied to crypto by FIN-2019-G001 |
| United Kingdom | In force since 1 Sep 2023 | FCA expectations include handling transfers to countries without the rule |
How to Get a Cryptocurrency Exchange Licence in the United Kingdom (FCA, 2026 to 2027)
To run a crypto exchange for UK customers in October 2026 you need FCA registration under the Money Laundering Regulations (MLRs) today, and you must apply for full FSMA authorisation between 30 September 2026 and 28 February 2027 to keep trading after 25 October 2027. The FCA's fee instrument FCA 2026/58 puts a trading platform application in pricing Category 7, and the FCA's prudential rules set a permanent minimum capital of £150,000 for operating a trading platform. Here is how the two regimes fit together and what each step costs.
Which UK Crypto Licence Do You Need: MLR Registration or FSMA Authorisation?
Today's regime is registration: since 10 January 2020 the FCA has supervised cryptoasset exchange providers and custodian wallet providers for AML and CTF under the MLRs. Registration covers money laundering controls, the Travel Rule and the financial promotions rules. It does not cover conduct, prudential or market abuse standards.
The new regime is authorisation under the Financial Services and Markets Act 2000, which the FCA calls the "new cryptoasset regulated activities". The fee instrument lists seven: operating a qualifying cryptoasset trading platform (QCATP), dealing in qualifying cryptoassets as principal, dealing as agent, arranging deals, safeguarding cryptoassets, arranging qualifying cryptoasset staking and issuing a qualifying stablecoin. An exchange with an order book is a QCATP; one that also runs its own wallets safeguards; one that fills client orders from inventory deals as principal. The FCA's September 2026 perimeter guidance (PS26/18) explains where each activity starts and stops. Overseas firms serving UK customers must also be authorised; there is no overseas exemption for a crypto exchange.
FCA Application Fees for a UK Crypto Exchange Licence
The FCA's Handbook Notice 144 (September 2026) confirms the application fee for each activity, and only the highest category is payable when one application covers several activities:
| Activity | Pricing category | Application fee |
|---|---|---|
| Operating a qualifying cryptoasset trading platform | 7 | £28,150 |
| Dealing as principal; safeguarding cryptoassets; issuing a qualifying stablecoin | 6 | £11,260 |
| Dealing as agent; arranging deals; arranging staking | 4 | £2,820 |
Firms applying for MLR registration and FSMA authorisation at the same time pay one fee, the higher of the two. Periodic (annual) fees do not start until the 2028/29 fee year.
Capital Requirements for UK Crypto Exchanges Under CRYPTOPRU
The FCA's prudential sourcebook for crypto firms, CRYPTOPRU, set out in Policy Statement PS26/12 (June 2026), requires the highest permanent minimum requirement (PMR) across a firm's permissions, plus a fixed overheads requirement and activity-based K-factors:
| Permission | Permanent minimum capital |
|---|---|
| Dealing in qualifying cryptoassets as principal | £750,000 |
| Issuing a qualifying stablecoin | £350,000 |
| Operating a qualifying cryptoasset trading platform | £150,000 |
| Safeguarding cryptoassets | £150,000 |
| Arranging qualifying cryptoasset staking | £150,000 |
| Dealing as agent; arranging deals | £75,000 |
A pure order-book exchange therefore needs £150,000; an exchange that also acts as market maker on its own book needs £750,000. Cryptoassets that are not admitted to a UK qualifying trading platform are deducted from regulatory capital, so holding your own illiquid token does not count.
UK Crypto Licence Timeline: Gateway, Decision and Transitional Run-Off
- 30 September 2026: gateway opened; applications go through the FCA's Connect system.
- 28 February 2027: gateway closes for firms that want the FCA to decide before commencement.
- 25 October 2027: the new regime commences. Firms that applied in the window but have no decision yet use a saving provision and may keep operating while the FCA finishes.
- After commencement: firms that applied late and are still pending enter a transitional provision by operation of law, which lets them perform pre-existing contracts only, with no new UK customers, for a maximum of two years. Firms that never applied must wind down UK business before 25 October 2027 or risk unauthorised business.
Step-by-Step: Applying for FCA Authorisation as a Crypto Exchange
- Scope your permissions. Map each product to the seven activities; a spot exchange with custody usually needs QCATP, safeguarding and often dealing as agent.
- Run a gap analysis against the FCA Handbook, CRYPTOPRU and the Consumer Duty, as the FCA's what you need to do page asks, and have the board sign off an implementation plan.
- Prepare the pack: regulatory business plan, financial projections showing PMR plus fixed overheads cover, compliance monitoring programme, safeguarding and reconciliation policies, ICT and operational resilience documents, and senior managers' applications.
- Submit through Connect and pay the fee (£28,150 for a trading platform).
- Answer FCA questions. FSMA's standard statutory timetable gives the FCA six months to decide a complete application and twelve months for an incomplete one, which is why the FCA says to apply early in the window.
- Build to the rules before approval. Your platform must already segregate client assets, log every transaction, run Travel Rule messaging and support the FCA's reporting formats when the FCA tests it.
Centralized Exchange Compliance Requirements: The Checklist
Compliance for centralized exchanges comes down to the same ten requirements in every market, even though the licence names differ. A centralized exchange (CEX) holds customer funds and matches orders itself, so it carries custody, market integrity and AML duties that a non-custodial DEX does not. Our comparison of centralized vs decentralized exchanges explains the structural difference; here is the compliance side.
- Licence or registration in every country you actively serve (MiCA CASP, FinCEN plus state licences, FCA, VARA, MAS, FIU-IND).
- KYC and customer due diligence with identity verification, sanctions and PEP screening and risk scoring before trading.
- Ongoing transaction monitoring with blockchain analytics and suspicious activity reporting (SARs or STRs).
- Travel Rule messaging for transfers to and from other VASPs, with self-hosted wallet checks where required.
- Segregated custody of client assets, reconciled to on-chain balances, with cold storage and key management policies.
- Capital and prudential cover (MiCA Class 3 €150,000; FCA PMR £150,000 to £750,000; MAS base capital by licence class).
- Market abuse controls: surveillance for wash trading, spoofing and insider dealing, which MiCA requires expressly.
- Consumer protection and marketing rules: risk warnings, cooling-off periods and approved promotions (the UK's financial promotions regime is the strictest).
- Operational resilience and security: DORA in the EU, ICT risk management, incident reporting and penetration testing.
- Tax reporting and record keeping: DAC8, Form 1099-DA, India's 1% TDS, and five-year retention of KYC and transaction records.
The licensing, KYC, security and tax sections below expand each item, and the compliance-by-design table turns them into software modules.
Crypto Exchange Compliance Requirements for Launch: Licensing, KYC/AML, Data, Security and Tax
Launching a crypto exchange that follows these rules builds credibility, earns user trust and opens doors to banks and payment partners.
Essential Regulations: Crypto Exchange Licensing and KYC/AML
The essential regulations every exchange must follow are licensing and KYC/AML.
- Crypto Exchange Licensing
Each jurisdiction has its own licence. The main ones in 2026 are FinCEN MSB registration plus state money transmitter licences in the US, a BitLicense in New York, a MiCA CASP authorisation in the EU, FCA registration (and from October 2027, FCA authorisation) in the UK, a VARA licence in Dubai, a MAS licence in Singapore and FIU-IND registration in India. An Electronic Money Institution (EMI) licence, sometimes listed for crypto, covers e-money, not crypto trading; you may need one only if you also issue e-money.
- KYC/AML Policies
KYC (Know Your Customer) and AML are the core of cryptocurrency exchange compliance. KYC verifies each customer's identity and screens them against sanctions and politically exposed person (PEP) lists. AML adds ongoing transaction monitoring, blockchain analytics, and suspicious activity reports (SARs in the US, STRs in the EU and India) to the financial intelligence unit. Both must follow a risk-based approach: stronger checks for higher-risk customers, products and countries.
Technical Compliance: Data Protection Laws
- Data Protection Laws
Data protection laws govern how user data is collected, stored and processed. The main ones are the GDPR in the EU and UK, the CCPA in California, Singapore's PDPA and India's Digital Personal Data Protection Act. They require clear privacy policies, lawful grounds for processing, data minimisation, breach notification and strong security for personal data.
Security Compliance: Cybersecurity, Due Diligence and Legal Opinions
- Cybersecurity Measures
Cybersecurity controls protect the exchange, its user data and its funds from attackers: two-factor authentication, TLS encryption, anti-phishing measures, key management and incident response. For how these controls fit together, explore the essential role of security in crypto exchanges. The relevant laws include:
- The EU's Digital Operational Resilience Act (DORA), which applies to MiCA-authorised CASPs from 17 January 2025 and sets rules for ICT risk management, incident reporting, resilience testing and third-party providers
- The GDPR, for security of personal data
- The NIS2 Directive, for essential and important entities in the EU
- The California Consumer Privacy Act (CCPA)
- Singapore's Personal Data Protection Act (PDPA)
These security measures align with regulatory requirements, protect user data and reduce the risk of fraud and cyber attacks.
- Due Diligence
Due diligence examines the exchange's compliance, legal standing and finances, and it runs both ways: regulators and banks run it on you, and you must run it on your vendors, liquidity providers and banking partners. The aim is to show that the platform is transparent, secure and safe for crypto trading.
- Legal Opinions
Before listing a token, exchanges need to know whether it is a security. In the US that means the Securities Exchange Act and the SEC's March 2026 taxonomy; in the UK, the Financial Services and Markets Act and the FCA's perimeter guidance; in the EU, whether the token falls under MiCA or under financial instruments law.
Legal opinions also help startups make sure user agreements, partnerships and vendor contracts are legally binding and enforceable.
Financial Licensing: MSB, VASP and CASP
- MSB
MSBs, or Money Services Businesses, offer services such as money transmission and currency exchange. In the US, FinCEN treats crypto exchangers as money transmitters, including foreign exchanges that serve US customers, so they must register as MSBs before launch. Registration builds credibility with customers and banks, but it is only the federal step: most states also require their own licence.
- VASP and CASP
A Virtual Asset Service Provider (VASP) is FATF's term for a business that exchanges, transfers, holds or issues virtual assets for others. Most countries use it in their AML laws. The EU uses its own term, Crypto-Asset Service Provider (CASP), under MiCA.
Tax Compliance: DAC8, Form 1099-DA and India's TDS
- Tax Obligations
Tax rules vary by country, and exchanges now report customer activity directly to tax authorities:
- EU: DAC8 has applied since 1 January 2026, requiring crypto-asset service providers to collect and report customer transaction data, with the first exchange of information by 30 September 2027. It is based on the OECD's Crypto-Asset Reporting Framework (CARF).
- US: brokers report digital asset sale proceeds to the IRS on Form 1099-DA, starting with 2025 transactions.
- India: exchanges deduct 1% TDS on transfers of virtual digital assets (section 194S of the 1961 Act, carried into section 393 of the Income-tax Act, 2025 from 1 April 2026), and users pay a flat 30% tax on gains.
- Global: FATCA and the Common Reporting Standard (CRS) still apply to fiat accounts, and CARF extends the same model to crypto.
These cryptocurrency exchange regulations protect the trading platform's financial integrity, transactions and data.
Legal Considerations: IP Rights and Terms of Service
- IP Rights
Intellectual property (IP) rights protect the platform's software, content, brand and inventions from unauthorised use.
- Copyright law: protects the website's content, software code and other creative work.
- Trademark law: protects the exchange's name, logo and brand identity.
- Patent law: protects genuinely new technical inventions used by the exchange, where patentable.
- ToS
Terms of Service (ToS) are the written agreement users accept to use the exchange. They set out user obligations, fees, custody terms, risk warnings and complaint routes. Under most regimes, including MiCA, users must be told their rights, how their assets are held and how to complain.
These are the common compliances and regulations for cryptocurrency exchange development. Proper licensing, tax registration and transparent terms are the foundation of a healthy crypto trading business.
Crypto Exchange Compliance in India: FIU-IND Registration and the 2026 Crackdown
In India, crypto exchange compliance starts with registration as a reporting entity with the Financial Intelligence Unit (FIU-IND) under the Prevention of Money Laundering Act (PMLA), and the obligation is activity-based: it applies to offshore exchanges that serve Indian users just as much as to Indian companies. Enforcement has stepped up in 2026, and "FIU compliant crypto exchange" has become the phrase Indian users search for before they deposit.
The Crypto Exchanges India Compliance Crackdown, 2024 to 2026
- June 2024 and January 2025: FIU-IND fined Binance ₹18.82 crore and Bybit ₹9.27 crore for serving Indian users without registration.
- 1 October 2025: the Ministry of Finance said FIU-IND had issued non-compliance notices to 25 offshore VDA service providers and that 50 VDA service providers had registered.
- 9 September 2026: FIU-IND issued notices to 15 more VDA service providers under Section 13 of the PMLA, naming Weex, Blofin, Rezorex, Bitunix, DigiFinex, Toobit, XT.com, Latoken, WOO X, Pionex, ChangeNow, SimpleSwap, Fixedfloat, WhiteBIT and Guardarian, and asked for their apps and URLs to be taken down in India under the IT Act.
The pattern is clear: unregistered exchanges lose Indian app-store and web access, then face penalties.
How to Check for an FIU Compliant Crypto Exchange in India
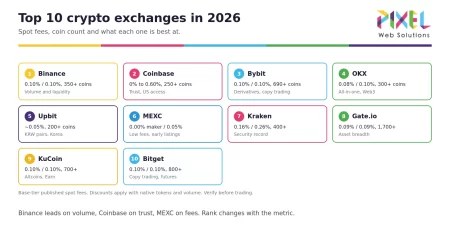
A trusted crypto exchange in India shows four things: its FIU-IND registration as a reporting entity, 1% TDS deducted on every eligible transfer and reported to the tax department, KYC with PAN and Aadhaar-based verification, and an Indian legal entity or grievance officer you can reach. If an exchange cannot show its FIU-IND registration, treat it as unregistered. Our ranking of the top crypto exchanges by volume and trust notes which global venues hold local registrations.
UAE Crypto Exchange Licence: VARA, ADGM FSRA and the Capital Market Authority
The UAE has three routes to a crypto exchange licence, and the right one depends on where you set up. Dubai (outside the DIFC) is regulated by VARA, Abu Dhabi Global Market by its Financial Services Regulatory Authority (FSRA), and the federal onshore market by the Capital Market Authority, which replaced the Securities and Commodities Authority on 1 January 2026.
- VARA (Dubai): exchange services need a VASP licence, with an AED 100,000 application fee and AED 200,000 a year in supervision fees under VARA's fee schedule. VARA's rulebooks v2.0 have applied since 19 June 2025, it published AML/CFT business risk assessment guidance on 12 June 2026, and on 6 October 2026 it issued a circular on reserve assets audit reports after reviewing every proof-of-reserves report filed in 2025. Our VARA licence cost guide gives a full first-year budget.
- ADGM FSRA (Abu Dhabi): the FSRA has regulated virtual asset activities since 2018, treats an exchange as a multilateral trading facility using virtual assets and only permits trading in Accepted Virtual Assets that pass its criteria. See the FSRA's virtual assets framework.
- Capital Market Authority (onshore): tokens that qualify as securities or commodities derivatives fall under the CMA, and payment tokens under the Central Bank of the UAE.
Singapore MAS Licence for Crypto Exchanges
MAS licenses digital payment token (DPT) services under the Payment Services Act as a standard or major payment institution, and since 30 June 2025 the Financial Services and Markets Act requires a separate Digital Token Service Provider licence for Singapore-based firms that serve only overseas customers, a licence MAS has said it will generally not issue. In practice, a Singapore exchange must serve Singapore customers under a PSA licence, meet MAS's custody, segregation and consumer-access rules, and comply with the Travel Rule and PDPA.
Compliance by Design: What Each Rule Means for Your Exchange Software
Most compliance failures are not missing policies. They are software that does not do what the policy says. On 6 November 2025 the Central Bank of Ireland fined Coinbase Europe €21,464,734 because faults in its transaction monitoring configuration left more than 30 million transactions, worth over €176 billion and about 31% of its transactions, unmonitored for 12 months.
Use this table to turn each rule into a build requirement:
| Rule | Exchange module | What the software must do |
|---|---|---|
| KYC and CDD (FATF R.10 and R.15, national AML laws) | Onboarding | Verify identity, screen sanctions and PEP lists, assign a risk score, block trading until approved |
| Ongoing monitoring and SAR/STR filing | Transaction monitoring | Screen every deposit, trade and withdrawal; alert on rules and risk scores; case management; coverage checks that prove no transaction type is skipped |
| Travel Rule (EU TFR, FinCEN, FCA) | Withdrawal and deposit pipeline | Send and receive originator and beneficiary data with other VASPs; hold transfers missing data; verify self-hosted wallets over €1,000 in the EU |
| Sanctions (OFAC, EU, UN, UK) | Onboarding, wallets, geo-controls | Screen names and wallet addresses; block sanctioned jurisdictions by IP and residence |
| MiCA custody and segregation | Ledger and wallets | Keep client assets segregated from company assets; reconcile ledger to on-chain balances |
| MiCA and DORA resilience | Infrastructure | ICT risk register, incident reporting, resilience testing, third-party register |
| Tax reporting (DAC8, 1099-DA, India TDS) | Reporting and ledger | Record cost basis and proceeds per user; withhold TDS where required; export regulator formats |
| Record-keeping | Audit log and data store | Keep KYC and transaction records for the legal retention period (typically five years) in tamper-evident storage |
Build these into the platform from the first release. Our guide to crypto exchange architecture shows where the compliance layer sits in the system.
Why Crypto Exchange Compliance Pays: Penalties, Trust and Bank Access
Cryptocurrency exchanges should adopt these regulations for healthy growth and long-term survival. Here are the key reasons, with recent evidence.
Avoiding Penalties and Shutdowns: Operating without the right licence is now expensive. KuCoin agreed to pay about $297 million and leave the US market after pleading guilty to running an unlicensed money transmitting business in January 2025. In India, FIU-IND's fines on Binance and Bybit were followed by the 2025 and 2026 notice rounds described above.
Building Trust: Cryptocurrency exchange regulations set a clear operating framework. By following them, exchanges show users a real commitment to secure trading practices, and licences are what users increasingly check first.
Protecting Investment: Regulations require custody segregation, capital, market abuse controls and fair dealing, which protect users' assets from theft, manipulation and insolvency.
Improving Operational Efficiency: Regulators set out operating requirements for each type of exchange. Designing to those requirements from the start avoids expensive rebuilds after an audit or licence review.
Accessing Global Markets and Banks: A MiCA authorisation passports across the EU, and a recognised licence is often the condition for opening bank accounts and payment partnerships. Compliance is what turns a local platform into a global one.
Enabling Active Data Protection: Licensing reviews examine KYC/AML controls, encryption standards, secure integrations and real-time fraud monitoring. Meeting them protects both users and the exchange from attacks and breaches.
Overall, cryptocurrency exchange compliance benefits traders and trading platforms alike. It is the key to launching a secure, trusted and future-ready crypto exchange business. For the other hurdles founders face, read our guide to the challenges in creating a crypto exchange.
Are All Crypto Exchanges Regulated, and Is a MiCA Licence Worth It? What Founders Ask on Reddit and Quora
The same five questions come up in every founder forum. Here are plain answers, with the rules behind them.
Are all crypto exchanges regulated?
No. Every exchange that serves customers in the EU, US, UK, UAE, Singapore, Hong Kong or India is required to be licensed or registered, but plenty of offshore venues still operate without the licence for the markets they reach, and non-custodial DEXs sit outside most licensing regimes because no company holds the funds. The gap is closing: ESMA told unauthorised firms to leave the EU in July 2026, FIU-IND is blocking unregistered apps in India, and KuCoin's $297 million US settlement shows the cost of serving a market without its licence.
How do you get a MiCA licence, and how long does it take?
You apply to the national competent authority in one member state, for example BaFin, the AMF, the Dutch AFM or the Malta Financial Services Authority, with a programme of operations, governance, capital, custody, ICT and AML documentation. Under MiCA Article 63 the authority checks completeness within 25 working days and must decide within 40 working days of a complete application, which it can pause while it asks for more information, so a realistic project runs six to twelve months from kick-off including the preparation. The licence then passports to all 27 member states, and a trading platform needs €150,000 of permanent capital.
What legal considerations apply to a white label crypto exchange?
The licence always belongs to the operator, never to the software vendor. If you buy a white label exchange, you still need your own MiCA, FCA, VARA or FIU-IND registration, your own AML policies and MLRO, your own terms of service and your own custody arrangements. What the vendor must give you is software that supports those duties: configurable KYC flows, transaction monitoring integrations, Travel Rule messaging, segregated wallets and audit logs. Ask for that list in the contract.
Why does compliance at most exchanges just mean paying a KYC vendor?
Because buying a vendor is the easy half. The Coinbase Europe case shows the hard half: the vendor was in place, but a configuration fault left 31% of transactions unmonitored for a year, and the fine was €21.5 million. Real compliance means risk-based rules you own, coverage testing that proves every transaction type is screened, trained staff who close alerts, and management information the board actually reads.
Can you launch an exchange from a country with no crypto law to avoid all this?
You can incorporate there, but the obligations follow your customers, not your registered office. FinCEN applies to foreign exchanges with US users, MiCA to anyone soliciting EU customers, the FCA to anyone marketing to UK consumers, and FIU-IND's duties are expressly "activity-based" and independent of physical presence. Geo-blocking and marketing restrictions are part of compliance too.
Kickstart Your Crypto Exchange with Compliance by Pixel Web Solutions
We hope this guide has given you a clear view of crypto exchange compliance, licences and regulations in 2026. Even if you have strong legal advisers, you still need a platform that does what your compliance manual promises. Pixel Web Solutions builds exchanges with the compliance layer designed in: KYC and sanctions screening, transaction monitoring integrations, Travel Rule messaging, segregated custody, audit logs and tax reporting, working alongside your legal counsel.
As a leading crypto exchange development company, we build legally sound crypto exchange platforms for long-term success. A white-label exchange costs $25,000 to $50,000 and a custom exchange $100,000 to $150,000+, and our white-label crypto exchange comes with compliance integrations ready to configure for your jurisdiction. If you're ready to build a rock-solid legal foundation for your crypto business, let's connect.
Frequently Asked Questions
Are crypto exchanges regulated?
Yes. In almost every major market, crypto exchanges must register or be licensed and follow AML rules. The EU licenses them under MiCA, the US through FinCEN and state regulators, the UK through the FCA, Dubai through VARA, Singapore through MAS and India through FIU-IND registration.
Who regulates crypto exchanges?
In the US, FinCEN (AML), the SEC and CFTC (securities and commodities), and state regulators such as NYDFS. In the EU, national authorities under MiCA, coordinated by ESMA. In the UK, the FCA. FATF sets the global AML standards that all of them follow.
What is a vital regulatory requirement for crypto exchanges?
KYC and AML, including the Travel Rule. Every licensing regime requires identity verification, sanctions screening, ongoing transaction monitoring and suspicious activity reporting, and failures here cause most enforcement actions.
What licence do I need to run a crypto exchange?
It depends on where your users are: a MiCA CASP authorisation for the EU, FinCEN registration and state licences (plus a BitLicense for New York) for the US, FCA registration now and FSMA authorisation from October 2027 for the UK, a VARA licence for Dubai, a MAS licence for Singapore and FIU-IND registration for India.
How much does a cryptocurrency exchange licence cost in the United Kingdom?
The FCA application fee for operating a qualifying cryptoasset trading platform is £28,150 (pricing Category 7), and you need at least £150,000 of permanent minimum capital, or £750,000 if you also deal as principal. Legal, compliance staff and systems costs come on top, and annual FCA fees start in the 2028/29 fee year.
How much capital does a crypto exchange need under MiCA?
A trading platform is a Class 3 CASP and needs at least €150,000 of permanent capital, or one quarter of the previous year's fixed overheads if that is higher. Custody and exchange services without a trading platform need €125,000; other services €50,000.
Is the CLARITY Act law?
No. The CLARITY Act passed the US House on 17 July 2025, but as of 26 October 2026 it has not passed the Senate, where a cloture vote on 15 September 2026 failed 49 to 50. The GENIUS Act on stablecoins is law, and the OCC issued its final implementing rule on 21 October 2026, effective 18 January 2027.
What is a crypto compliance certification?
It is a professional credential for compliance staff rather than a licence for the exchange. Industry bodies such as ACAMS offer crypto-specific anti-financial-crime certifications, and regulators expect an exchange to appoint a qualified Money Laundering Reporting Officer (MLRO) or compliance officer. The certification helps your licence application; it does not replace it.
How do I know an exchange is compliant?
Check the regulator's public register: ESMA's MiCA register in the EU, the FCA register in the UK, NYDFS for New York, VARA's public register in Dubai and MAS's directory in Singapore. A compliant exchange also publishes its licences, legal entity and complaint process, which are the visible signs of real crypto exchange compliance.